Deepseek
Addressing Climate Change: Five Strategies to Cut Commercial Property Insurance Costs
Climate change-induced disasters such as tornadoes and floods have caused U.S. commercial property insurance costs to surge, rising 15% in 2022, the largest increase in over three decades. CFOs face a seller's market and need to adopt new strategies. Expert recommendations include: comprehensively reviewing risk tolerance, strengthening collaboration with insurers, enhancing loss prevention, exploring innovative products like parametric insurance, and leveraging data analytics.
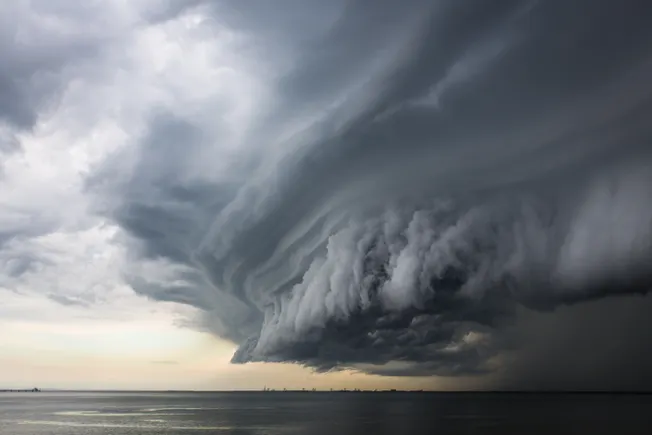
Disasters triggered by climate change, such as tornadoes, floods, and hurricanes, are upending the foundations of CFO risk management. Commercial property insurance costs in the U.S. are soaring, rising 15% in 2022, the largest increase in over three decades, according to the Insurance Information Institute. In the first half of 2023, commercial property claim costs surged 30%, as reported by the Swiss Re Institute.
Severe weather has created "the most challenging property market since 9/11," said Brandon Thompson, senior vice president of risk at Houston-based commercial real estate firm Transwestern. "The coming years will be fraught with difficulty."
Thompson noted in an interview that CFOs face a seller's market for commercial property insurance, with underwriters raising premiums and withdrawing from high-risk areas. "You can't just walk down the street and find an insurance company anymore."
The turmoil brought by global warming is forcing CFOs and chief risk officers to precisely assess corporate vulnerabilities and minimize insurance costs, according to risk management experts. Solutions include forging closer partnerships with insurers, reinforcing buildings to withstand damage, and adopting new insurance structures and advanced data analytics.
"If you stick to old methods, you won't move forward," said Zaheer Hooda, head of North America at London-based company Cytora.
The frequency of climate change-induced disasters shows no signs of abating. As of early November this year, the U.S. experienced 25 weather-related disasters, each causing at least $1 billion in losses, according to the National Oceanic and Atmospheric Administration (NOAA). From 1980 to 2022, the U.S. faced an average of only about 8 such disasters annually (inflation-adjusted).
NOAA stated this month in the U.S. National Climate Assessment that billion-dollar disasters now strike the U.S. on average every three weeks, compared to once every four months in the 1980s (based on inflation-adjusted data).
The footprint of destruction is expanding. This year, convective storms with heavy rain, lightning, hail, and strong winds have pushed further north into the Great Lakes region, broadening the scope of vulnerability for insurers and businesses.
In the first half of 2023, convective storms caused $34 billion in insured losses in the U.S.—a six-month record—accounting for 68% of global insured natural catastrophe losses, according to Swiss Re data.
When assessing potential loss risks, insurers have long balanced policy risk between disaster-prone coastal states like Florida and California and lower-risk central regions. "As convective storm losses grow significantly in the central U.S., this balance is no longer effective," Thompson said.
Over the past decade, the cost of extreme weather to insurers has soared, outpacing inflation-driven increases in labor and building material costs—even considering the high price pressures that began in late 2021. So-called claim severity (the average cost per claim) has surged 150% over the past decade, roughly six times the rate of inflation, said David Hemry, director of commercial strategy at LexisNexis Risk Solutions.
Facing severe weather losses, several insurers are seeking to reduce exposure. State Farm, one of several underwriters exiting California, announced in May it would stop accepting new applications for commercial and personal property insurance in the state. Nationwide announced in June it would implement unspecified risk-reduction measures in small and medium-sized commercial property insurance in unspecified states.
In recent years, hail has severely impacted several regions, especially the Interstate 35 corridor in Texas and the Denver and other parts of Colorado, Hemry said in an interview. Underwriters that could accurately predict claims in many areas for years can no longer do so.
"Insurers in Arkansas, Illinois, Kentucky, and Indiana are in a particularly precarious position," said Bill Clark, CEO of Demex Group, in an email response.
Meanwhile, reinsurers—providers of lifeline financing for insurers—are pulling back. They have raised premiums by 30% to 50% this year for U.S. insurers with catastrophe losses, according to an order signed by California Governor Gavin Newsom in September aimed at strengthening the state's private insurance market.
"The impact of climate change and billion-dollar losses put enormous pressure on reinsurance, which ultimately determines what you can buy in the retail insurance market," Thompson said.
As insurance costs rise, CFOs and finance executives responsible for risk management and insurance may gain greater influence in the C-suite, he said. "Risk management will need a bigger seat at the table than it has had in the past few years."
Given a larger role, CFOs can limit climate change costs through five measures, according to risk management experts:
1. Comprehensively review risk tolerance
Risk management experts say CFOs who thoroughly assess their company's ability to withstand extreme weather damage will adapt more quickly to rising commercial property insurance premiums and the prospect that inflation could exceed the Federal Reserve's 2% target in the coming years. CFOs should no longer view insurance as a routine expense item carried over annually. Finance executives may need to adjust insurance portfolios more frequently and use data simulating weather as well as labor, construction, and other costs to assess company needs more precisely. CFOs may find they need to budget more for insurance, at least for the foreseeable future. As always, shopping around for high-value insurance may help control costs, Hooda said in an interview. However, CFOs need to keep the fundamental principle in mind, Hooda said: "First, accept the reality of premium increases and adjust your profit impact accordingly."
2. Strengthen collaboration with insurers
Experts say that as the commercial property insurance market adapts to the shock of extreme weather, CFOs should increase the frequency and depth of contact with underwriters. Finance executives should contact insurers 180 days before application deadlines, rather than the usual 90 days. They should also use data to detail ways to reduce risk and limit losses. "Make sure you submit a high-quality application with loss control explanations," Thompson said.
3. Redouble efforts to avoid losses
Risk management experts say CFOs should not overlook reliable strategies to reduce insurance costs through improvements such as installing wind-resistant shutters, flood barriers, and fire suppression systems. According to the National Institute of Building Sciences, for every $1 invested in measures to limit property damage, such as retrofits or adopting updated building codes, up to $13 in losses can be avoided. "It's not just property risk," Hemry said, "there's also liability risk from personal injury, trespassing, and more."
Many commercial property owners have neglected maintenance after occupancy rates fell during the pandemic, risk management experts say. Instead, with the Federal Reserve raising benchmark interest rates to a 22-year high, CFOs are focused on the high cost of refinancing debt. "We're in a vicious cycle: as occupancy declines and loans mature, there may be less investment in properties," Thompson said, "which only drives claim severity higher."
4. Consider insurance innovation
Alternatives to traditional commercial property insurance can fill gaps left by policies reduced or withdrawn due to frequent severe weather, risk management experts say. CFOs responsible for properties in disaster-prone areas may want to consider so-called parametric insurance, which pays a fixed amount based on the characteristics of a damaging event, rather than the cost of repairs. CFOs often purchase parametric insurance as a supplement to or replacement for traditional policies. "From a CFO perspective, it provides a certain stability," Hooda said, while noting that loss-to-payout ratios are typically less favorable than traditional policies.
5. Deepen data analytics
"Big data has existed since insurers have existed," said Gary Sullivan, senior director of emerging risks at the American Property Casualty Insurance Association, in an interview. Today, however, insurers can use advanced analytics to measure risks like wind and wildfire more precisely, identify vulnerabilities, and uncover new opportunities. "Historically, the insurance industry has been quite slow-moving," Hemry said, "it's inherently conservative."
Insurance startups are disrupting established companies by using new data collection and analysis methods. For example, computer analysis of roof photos taken from aircraft can precisely assess risk across wide areas, reducing claims and premiums. InsurTech "integrates with underwriters to help them do things they couldn't do in the past 100 years because it's not in their nature," Hemry said.
CFOs should ask underwriters how they use artificial intelligence, data analytics, and advanced technology to measure risk, risk management experts say. Additionally, when drafting insurance applications, CFOs should consider using customized risk management systems "to tell a story that avoids being lumped into general market trends," Thompson said.
Ultimately, higher premiums driven by destructive weather may attract new capital into the insurance industry. The commercial property insurance market will stabilize, and CFOs may find risk management costs more manageable. "People will see it as an entrepreneurial opportunity, and they'll join," Hooda predicted, "over time, you'll see improvement."